KevinParsells.net · Consumer education

Mortgage options for complex or non-traditional income

Educational information for people whose income does not fit a simple payroll pattern. It is not a product menu, loan application, credit decision, rate quote, commitment to lend, or promise that a Non-QM or alternative-income option is available.

General education only—not a mortgage application, loan offer, rate quote, recommendation, approval, or statement of licensing availability.

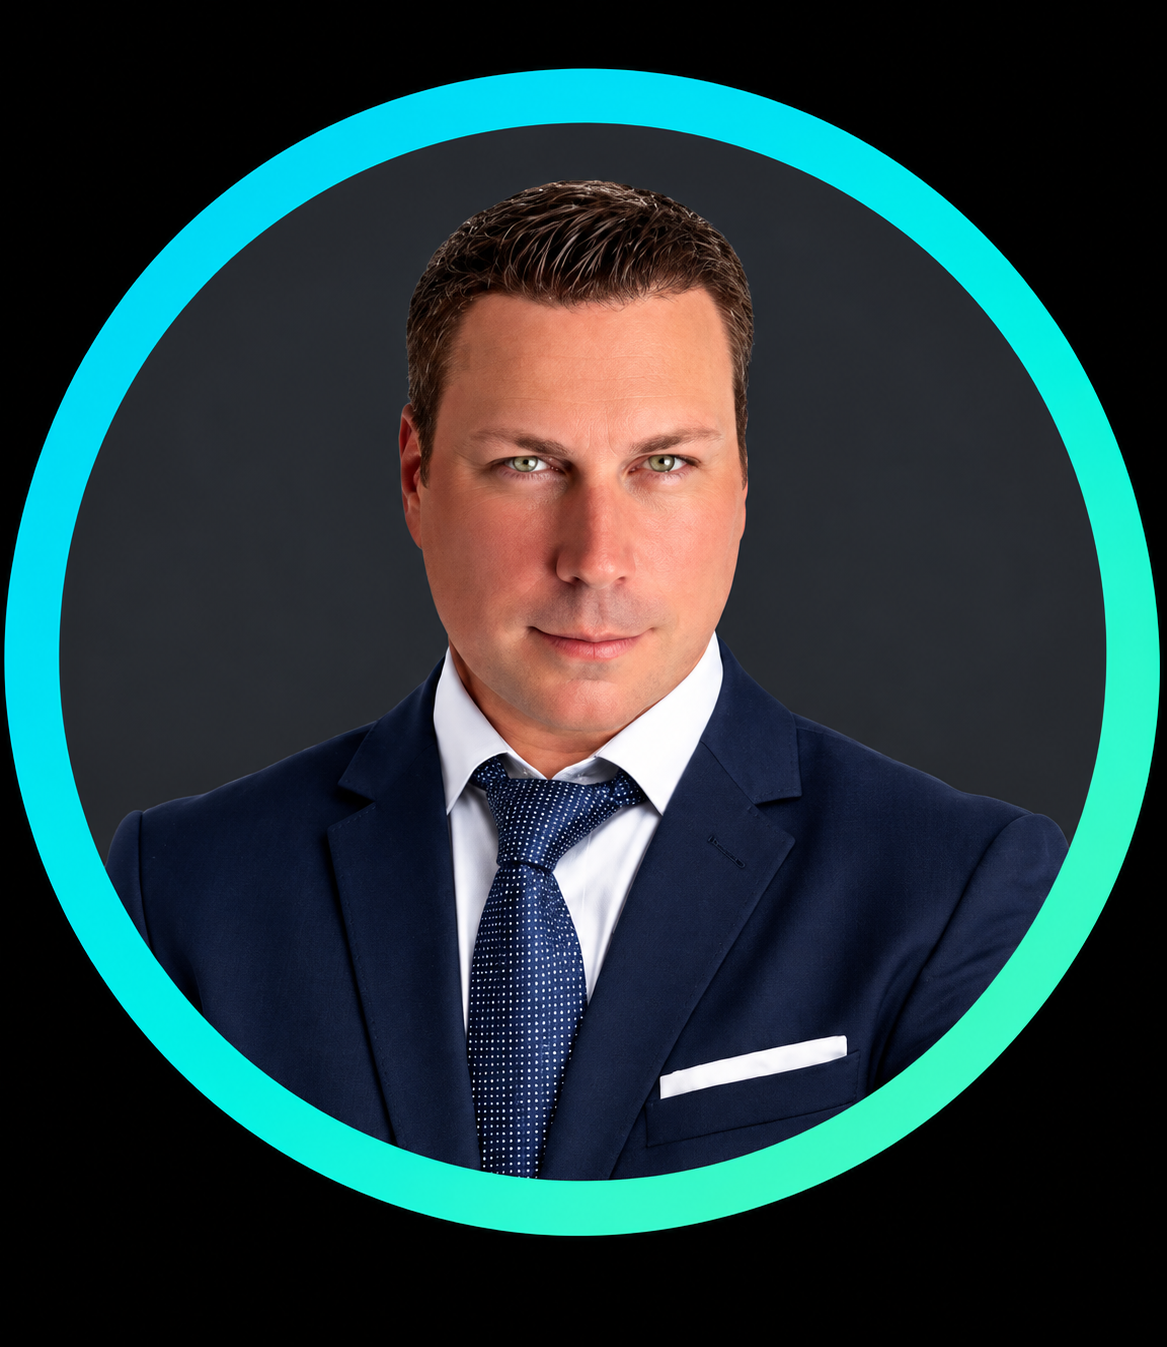
Kevin W. Parsells
Kevin W. Parsells · Director of Strategic Growth, Cornerstone First Mortgage · NMLS #241784
Verified professional context

Cornerstone First Mortgage lists Kevin W. Parsells on its official professional profile. Next Level Coaching is a separate coaching and education platform.

Use the right channel

For a mortgage application or individualized lending process, use only Kevin’s official Cornerstone First Mortgage profile.

Visit the official profile
01

Start with the income story, not a label

Self-employment, business ownership, commission, bonus, multiple income sources, recent changes, or substantial assets can make a mortgage conversation more detailed. Begin by identifying the questions that need clarification: how income is earned, whether it is consistent, what the property and occupancy plan are, and which facts a licensed professional would need to verify. An educational conversation can organize those questions; it does not determine eligibility or replace underwriting.

02

What Non-QM and alternative-income education can explain

Non-QM generally describes mortgage options that do not fit the standard qualified-mortgage framework or that use a different approach to documenting or evaluating repayment ability. It is not one uniform program and does not establish that any lender offers a particular option. The CFPB explains that, for covered mortgages, lenders generally must make and document a reasonable, good-faith ability-to-repay determination; the transaction and applicable rules matter.

03

Compare documentation and tradeoffs in context

Different documentation approaches can carry different underwriting methods, pricing, fees, down-payment or reserve expectations, debt-to-income treatment, prepayment provisions, property or occupancy limits, and consumer protections. A conventional or government-backed path, an alternative documentation approach, or no suitable path may be appropriate depending on verified facts. If another lender declined a request, that does not imply approval elsewhere; it can be a reason to ask which additional financing options could be considered.

04

Keep this inquiry non-financial

Use the consultation to ask high-level questions rather than to submit an application or documents. Do not send Social Security numbers, tax returns, pay stubs, bank statements, account numbers, login credentials, identity documents, income amounts, or other sensitive financial details through this form, email, or the scheduling link. If an application is appropriate, sensitive information belongs only in an approved employer application system after the proper review.

05

Verify authority before any financing decision

A state selection helps organize the conversation but does not establish licensing, company or branch authority, or product availability. The CFPB directs consumers to NMLS Consumer Access to check whether a company or professional is authorized in their state. Current individual, company, branch, and product authority must be confirmed for the relevant state by an appropriately licensed representative; no nationwide availability is represented here.

The next step

Request an educational mortgage-information consultation to organize your alternative-income questions. A consultation is not an application or approval, and no sensitive financial details should be submitted here.

Optional reply request

Ask for a reply before scheduling.

Share only the contact details needed for the team to respond. This stores a reply request; it is not a mortgage application, a financial-document upload, or a marketing subscription.

Questions, answered clearly

Know the boundary before you choose a time.

What does Non-QM mean?

Non-QM generally refers to mortgage options that do not fit the standard qualified-mortgage framework or use an alternative approach to documenting or evaluating a borrower’s ability to repay. Exact requirements and availability depend on the lender, product, property, transaction, borrower profile, and applicable rules. This education page does not establish that any specific option is available.

Who may want to ask about alternative-income education?

People with self-employment, business income, commission, bonus, multiple income sources, recent income changes, or substantial assets may want to understand documentation questions. That does not mean a person qualifies or that a Non-QM option is appropriate.

Can a prior bank decline be reversed here?

No approval is promised. A prior decline can prompt a question about additional financing options that could be considered, but any outcome depends on current authority, product availability, underwriting, verified documentation, and the transaction facts.

Will an alternative-income mortgage cost more?

It may involve different rates, fees, reserves, down-payment expectations, prepayment terms, documentation requirements, or other limitations depending on an actual transaction. Compare the total cost and features of any written offer; no rate, term, or cost is advertised here.

Can I send tax returns, pay stubs, or bank statements here?

No. Keep this inquiry non-financial. Do not submit sensitive documents or details through this page, email, or the scheduling link. If an application is appropriate, use only an approved employer application system after proper review.

Does this page mean financing is available in my state?

No. No nationwide or state-specific availability is claimed. State, company, branch, individual, and product authority must be verified for the actual transaction by an appropriately licensed representative.

Does booking a consultation create an application?

No. Booking uses the existing mortgage-information consultation and is an educational contact request. It is not an application, prequalification, commitment to lend, or guarantee of approval.